As of 30 October 2026, Coles reported revenue growth of 2.2 percent year on year to 11.2 billion dollars for the first quarter of fiscal 2027, with its main supermarket segment up 2.7 percent on a comparable basis. E-commerce grew 22.9 percent, the strongest area in the result. Woolworths reported 19.4 billion dollars in sales for the same period, up 4.7 percent, and the ABS put annual headline inflation at 4.3 percent in the 12 months to September.
Online is carrying a slow quarter
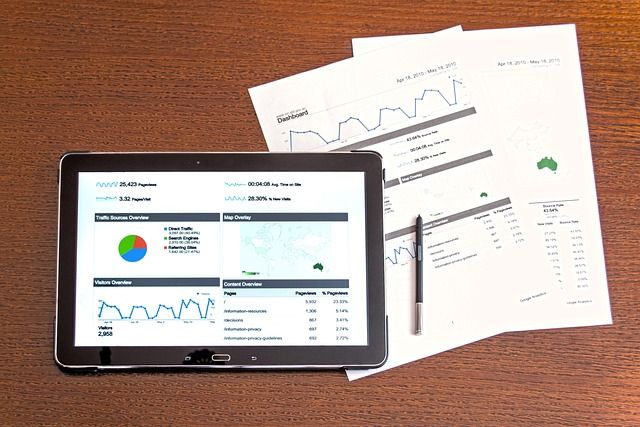
When total growth is 2.2 percent and online growth is 22.9 percent, the channel mix is moving faster than the top line suggests. Every percentage point that shifts online changes the cost structure underneath: picking labour replaces shelf replenishment, delivery slots replace checkout capacity, and the last metre becomes a paid service rather than a free one.
Grocery is the hardest category for that shift, because baskets are heavy, margins are thin and substitution rates are high. A retailer that grows online quickly without fixing fulfilment economics simply moves profit from stores to vans. The number to watch next is not online growth, it is online contribution margin.
Value conscious shoppers change the assortment
Coles said customers remain value-conscious, shopping across multiple retailers and focusing more on promotions and loyalty programs. That behaviour hits the middle of the range hardest. Premium own brand lines hold up, entry price lines hold up, and the standard branded product in between loses share to whichever banner is running the better offer that week.
Multi-retailer shopping also breaks the assumption that a household has a primary store. If a shopper splits a weekly basket across two banners, loyalty program data undercounts their real spend, and the retailer's view of share of wallet becomes unreliable. Category growth planning built on that data will systematically overstate loyalty and understate switching.
What the result means for suppliers
Suppliers reading this result should treat online and in store as two different shelf problems. On a screen, the first screen of results is the entire shelf, and ranking is decided by availability, price and content quality rather than by physical position. A brand that wins the aisle can still lose the search result.
The promotional calendar also matters more than it used to. When shoppers compare offers across banners, the week a promotion runs determines whether it is seen at all. Suppliers that plan promotions without checking the competing banner's calendar are effectively funding a discount that lands on a week when nobody is comparing.
Fulfilment economics decide the ceiling
Online grocery growth has a ceiling set by delivery cost per order, not by demand. Dense suburban routes work; sparse regional routes do not. That is why the channel mix shifts fastest in metropolitan postcodes and barely moves elsewhere, and why national online growth numbers hide very different local realities.
Loyalty data needs recalibration
If households split baskets, loyalty programs capture a declining share of true spend. Retailers that keep modelling share of wallet from loyalty data alone will misread their own performance. Cross retailer panel data, which is expensive and slower, is the only way to see the full picture, and it is worth the cost in a market this contested.
| Metric | Coles | Woolworths | Context |
|---|---|---|---|
| Quarterly sales | 11.2 billion dollars | 19.4 billion dollars | Different store bases |
| Growth | 2.2 percent | 4.7 percent | Coles supermarket segment 2.7 percent comparable |
| Online growth | 22.9 percent | Not disclosed in the report | Fastest growing channel |
| Inflation backdrop | 4.3 percent | 4.3 percent | ABS 12 months to September |
How to test the read
Separate volume from price before drawing conclusions. A 2.2 percent revenue gain against 4.3 percent inflation implies falling real volumes, which is a very different story from flat volumes with modest price growth. Retailers rarely disclose the split, so the check has to come from basket level data or supplier shipment figures.
Then check the promotional share of sales. If a banner grows by discounting more deeply, the growth is rented rather than earned, and it reverses when the funding stops. Suppliers should ask what proportion of the category sold on promotion in the quarter, and compare it with the same quarter last year.
FAQ
How did Coles perform in the quarter?
Revenue grew 2.2 percent year on year to 11.2 billion dollars, with the main supermarket segment up 2.7 percent on a comparable basis. E-commerce was the strongest area, growing 22.9 percent.
How does that compare with Woolworths?
Woolworths reported 19.4 billion dollars in sales for the same period, up 4.7 percent year on year. Coles grew more slowly against a smaller base, which is why the gap drew investor attention.
What are shoppers doing differently?
Coles said customers remain value-conscious, shopping across multiple retailers and focusing more on promotions and loyalty programs. The ABS put annual headline inflation at 4.3 percent in the 12 months to September.
Why does online matter more than the headline number?
Online growth of 22.9 percent against total growth of 2.2 percent means the channel mix is shifting fast. Basket economics, fulfilment cost and media revenue all change when a tenth of sales moves online.