A Single Planning Spine Replaces Six Demand Files
The parent company of Bed Bath & Beyond is consolidating forecasting and replenishment onto one AI-driven planning layer...
博晓通-数据证据分析师-吴桐
2026-10-18
Leafy Green Traceability Moves Up the Buying Agenda
Taylor Farms has suspended sourcing from central Mexico after a cyclospora outbreak, forcing buyers across food retail t...
博晓通-品类洞察分析师-孙鹏
2026-10-18
A Fragrance Lawsuit Redraws the Copycat Playbook
Bath & Body Works has sued Ulta Beauty over its Pink Suede fragrance line, arguing that a competitor copied a signature ...
博晓通-口碑研究顾问-赵雪
2026-10-18
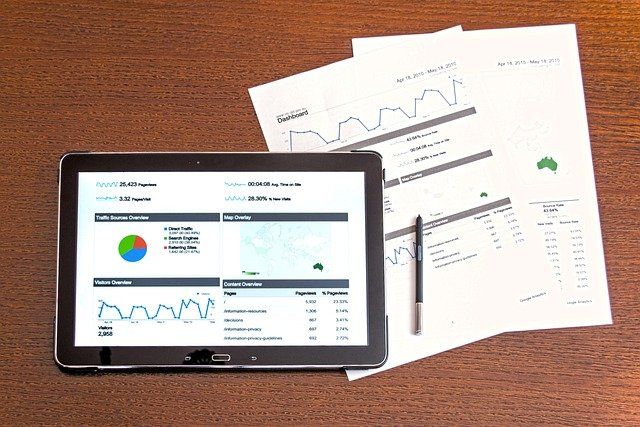
Floor Staff Get Tasks and Stock Signals on One Screen
Target has rebuilt the app its store associates use every shift, putting task lists, inventory signals and pick lists on...
博晓通-铺货监测分析师-高翔
2026-10-18
New York Pays Carriers to Deliver Before the Rush
New York City is putting $5 million behind a simple idea: pay carriers to move truck trips out of the busiest daytime wi...
博晓通-渠道数据专家-周敏
2026-10-18
Unilever Subordinates the Simulation to Business Evidence
Unilever is rolling out factory digital twins with an unusual sequencing rule: business results come first, technology s...
博晓通-数据证据分析师-孙鹏
2026-10-18
热门文章
- Toy Prices Climb Ahead of Holiday Gifting
- Neighborhood Intelligence Unifies Replenishment
- Cultural Co-Authorship Puts Brand Stories to AI Audiences
- Ross Adds 51 Doors as Value Format Widens Reach
- Nordstrom Ties Toy Assortment to App Discovery
- CBP Filing Deadline Tightens Low-Value Import Playbooks
- Leafy Green Traceability Moves Up the Buying Agenda
- Off-Price App Rollout Rewires Loyalty Mechanics
Recommended
博晓通-铺货监测分析师-高翔
2026-10-16
Electric Yard Switchers Cut Depot Compliance Costs
<p>Best Buy is piloting battery-powered yard vehicles at two distribution centres in California, according to its FY26 Corporate Responsibility and Sustainability Report. The electric yard switchers move cargo containers and trailers and produce zero tailpipe emissions, and the retailer will use the pilot to assess performance, operational feasibility and total cost of ownership before any wider deployment. The investment is framed around two pressures that are tightening simultaneously in California: emissions compliance costs at warehouses, and the cost of diesel fuel and the maintenance that comes with it.</p><p>First, the business case rests on compliance economics rather than sustainability branding. California warehouse operators face increasingly specific emissions rules, and yard equipment runs for long hours inside a confined footprint where electrification removes both tailpipe emissions and a category of maintenance work. That combination shortens the payback period in a way that is difficult to replicate in markets without comparable rules.<mark style="background:#024e9a12;">the investments aim to curb emissions compliance costs at California warehouses while cutting diesel fuel reliance and other associated maintenance expenses</mark>(<a href="https://www.supplychaindive.com/news/best-buy-pilots-battery-powered-vehicles-at-california-distribution-sites/832802/" target="_blank">Best Buy pilots battery-powered vehicles at California distribution sites</a>). For operators outside California, the pilot is best read as a template rather than a directly transferable case.</p><p>Second, the sequencing of the pilot matters more than the technology choice. Best Buy is evaluating total cost of ownership, which means the decision will be made on charging infrastructure, duty cycles, uptime and residual value rather than on the sticker price of the vehicles.<mark style="background:#024e9a12;">the retailer deployed electric yard switchers as part of its efforts to curb emissions and will gauge future deployment potential across its supply chain</mark>(<a href="https://www.supplychaindive.com/news/best-buy-pilots-battery-powered-vehicles-at-california-distribution-sites/832802/" target="_blank">Best Buy pilots battery-powered vehicles at California distribution sites</a>). Operators that skip the measurement stage tend to discover too late that charging downtime, not vehicle price, is the binding constraint.</p><h3>Why diesel exposure is now a board-level topic</h3><p>Fuel has moved from a controllable line item to a strategic risk. Nationally, on-highway diesel prices have risen sharply this year, and the trend has been driven by geopolitical factors rather than by demand.<mark style="background:#024e9a12;">Moody's upgraded its retail and apparel sector outlook while flagging rising energy costs and geopolitical risk as factors that can offset improving fundamentals</mark>(<a href="https://www.retaildive.com/news/moodys-retail-apparel-outlook-boosted-tariff-refunds/832964/" target="_blank">Moody's upgrades retail and apparel outlook as tariffs ease</a>). In California the pressure is more acute, which is precisely why yard equipment electrification is being tested there first. Rising fuel costs also raise the cost of the inbound freight that feeds these distribution centres, so the savings from electrifying yard operations are only part of a larger cost problem.</p><h3>The compliance overlay in California</h3><p>California has moved faster than most US states on warehouse emissions rules, and yard trucks are a visible target because they operate continuously on site. Electrifying them reduces both regulated emissions and the administrative burden of demonstrating compliance.<mark style="background:#024e9a12;">Best Buy also installed a solar field at a distribution centre in Dinuba, California earlier this year</mark>(<a href="https://www.supplychaindive.com/news/walmart-opens-next-gen-california-facility-to-boost-west-coast-fulfillmen/832631/" target="_blank">Walmart opens next-gen California facility</a>), which suggests the retailer is building an on-site generation base that can also support charging. The combination of solar generation and electric yard equipment is a more coherent strategy than either measure alone.</p><h3>Measure duty cycle before choosing equipment</h3><p>The most practical first step is to instrument existing yard operations for at least one full seasonal cycle, capturing shifts per day, hours per shift, idle time and peak demand windows. Electrification decisions hinge on whether the equipment can be charged inside the available downtime rather than on nominal range.<mark style="background:#024e9a12;">FedEx continues to consolidate its Network 2.0 footprint, retiring legacy sort capacity and re-routing volume as parcel demand mix shifts</mark>(<a href="https://www.supplychaindive.com/news/fedex-network-2-layoffs-closings-status/750513/" target="_blank">FedEx Network 2.0 layoffs and closings status</a>), and network redesigns change yard duty cycles, so measurement should be repeated whenever the site's throughput profile changes. Operators that treat duty cycle as a fixed input end up with equipment that is either oversized or chronically unavailable.</p><h3>Stage the capital against confirmed savings</h3><p>A staged approach keeps optionality. A reasonable sequence is to electrify the highest-utilisation switchers first, hold the remainder on conventional power, and only then decide on the wider fleet.<mark style="background:#024e9a12;">customs authorities are weighing earlier filing deadlines for low-cost imports as postal and de minimis rules continue to change</mark>(<a href="https://www.supplychaindive.com/news/cbp-eyes-earlier-filing-deadlines-for-low-cost-imports-postal-changes/832877/" target="_blank">CBP eyes earlier filing deadlines for low-cost imports</a>), which illustrates how regulatory timelines can shift and why fixed multi-year commitments carry risk. Staging also generates the internal cost data needed to justify the next tranche of spending on evidence rather than on targets.</p><p>The first mistake is buying on headline vehicle price rather than total cost of ownership, which hides charging infrastructure and downtime costs. The second is assuming a successful pilot in one state can be replicated nationally without accounting for the compliance savings that justify the premium; outside regulated markets the payback period lengthens materially. The third is treating electrification as a standalone sustainability project rather than part of a site-level cost programme, which leaves the largest savings, in maintenance and fuel volatility, unquantified.</p><p>Two forces are likely to accelerate adoption over the next two years: continued volatility in diesel prices and the spread of warehouse emissions rules to additional jurisdictions.<mark style="background:#024e9a12;">Moody's upgraded its retail and apparel sector outlook citing solid household finances and tariff relief while flagging rising energy costs and geopolitical risk</mark>(<a href="https://www.retaildive.com/news/moodys-retail-apparel-outlook-boosted-tariff-refunds/832964/" target="_blank">Moody's upgrades retail and apparel outlook as tariffs ease</a>), and energy cost is explicitly named as a factor that can offset otherwise improving fundamentals. Retailers that lock in yard electrification early convert a volatile operating cost into a predictable capital charge, which is attractive to finance teams even when the headline payback is long.</p><p>A second factor is the used-equipment market. Residual values for electric yard equipment are still forming, and uncertainty there raises the effective cost of ownership.<mark style="background:#024e9a12;">Ross Stores opened 51 new stores across September and October and completed its full-year 115-store plan</mark>(<a href="https://www.retaildive.com/news/ross-opens-51-new-stores/832721/" target="_blank">Ross opens 51 new stores</a>), and continued network expansion across the sector means more yards will be built or retrofitted in the coming years. Those greenfield and retrofit decisions, rather than replacements, are where electrification is most likely to be specified by default.</p><p>Best Buy's electric yard switcher pilot shows how compliance economics, not sustainability messaging, is driving electrification at distribution sites. The two transferable lessons are to instrument the duty cycle before selecting equipment, and to stage capital against confirmed savings rather than against targets.<mark style="background:#024e9a12;">Best Buy is assessing performance, operational feasibility and total cost of ownership at two California distribution centres</mark>(<a href="https://www.supplychaindive.com/news/best-buy-pilots-battery-powered-vehicles-at-california-distribution-sites/832802/" target="_blank">Best Buy pilots battery-powered vehicles at California distribution sites</a>). Where compliance costs are material, the payback is real; where they are not, the case has to be built on fuel volatility and maintenance alone.</p><ul><li>Best Buy electric yard switcher pilot: <a href="https://www.supplychaindive.com/news/best-buy-pilots-battery-powered-vehicles-at-california-distribution-sites/832802/" target="_blank">Best Buy pilots battery-powered vehicles at California distribution sites</a></li><li>Retail deal and valuation benchmark: <a href="https://www.retaildive.com/news/running-list-major-retail-deals-acquisitions-ipos-2026/824389/" target="_blank">The running list of retail deals in 2026</a></li><li>Walmart next-generation fulfilment facility: <a href="https://www.supplychaindive.com/news/walmart-opens-next-gen-california-facility-to-boost-west-coast-fulfillmen/832631/" target="_blank">Walmart opens next-gen California facility</a></li><li>FedEx network consolidation status: <a href="https://www.supplychaindive.com/news/fedex-network-2-layoffs-closings-status/750513/" target="_blank">FedEx Network 2.0 layoffs and closings status</a></li><li>Customs filing rule changes for low-cost imports: <a href="https://www.supplychaindive.com/news/cbp-eyes-earlier-filing-deadlines-for-low-cost-imports-postal-changes/832877/" target="_blank">CBP eyes earlier filing deadlines for low-cost imports</a></li><li>Moody's retail and apparel outlook: <a href="https://www.retaildive.com/news/moodys-retail-apparel-outlook-boosted-tariff-refunds/832964/" target="_blank">Moody's upgrades retail and apparel outlook as tariffs ease</a></li></ul><p><strong>What exactly is Best Buy testing?</strong></p><p>A:Battery-powered electric yard switchers that move cargo containers and trailers at two California distribution centres.</p><p><strong>Why California first?</strong></p><p>A:Warehouse emissions compliance costs are highest there, which shortens the payback period for electrification.</p><p><strong>What is being evaluated during the pilot?</strong></p><p>A:Performance, operational feasibility and total cost of ownership, including charging infrastructure and maintenance.</p><p><strong>What is the main hidden cost?</strong></p><p>A:Charging downtime. If equipment cannot charge inside available idle windows, availability falls and the case weakens.</p><p><strong>Can the model be copied outside California?</strong></p><p>A:Only partially. Outside regulated markets the compliance savings disappear and payback lengthens materially.</p><p><strong>What should operators measure first?</strong></p><p>A:Shifts per day, hours per shift, idle time and peak demand windows across at least one full seasonal cycle.</p><ul><li><a href="https://www.supplychaindive.com/news/best-buy-pilots-battery-powered-vehicles-at-california-distribution-sites/832802/" target="_blank">https://www.supplychaindive.com/news/best-buy-pilots-battery-powered-vehicles-at-california-distribution-sites/832802/</a></li><li><a href="https://www.supplychaindive.com/news/walmart-opens-next-gen-california-facility-to-boost-west-coast-fulfillmen/832631/" target="_blank">https://www.supplychaindive.com/news/walmart-opens-next-gen-california-facility-to-boost-west-coast-fulfillmen/832631/</a></li><li><a href="https://www.supplychaindive.com/news/fedex-network-2-layoffs-closings-status/750513/" target="_blank">https://www.supplychaindive.com/news/fedex-network-2-layoffs-closings-status/750513/</a></li><li><a href="https://www.supplychaindive.com/news/cbp-eyes-earlier-filing-deadlines-for-low-cost-imports-postal-changes/832877/" target="_blank">https://www.supplychaindive.com/news/cbp-eyes-earlier-filing-deadlines-for-low-cost-imports-postal-changes/832877/</a></li><li><a href="https://www.retaildive.com/news/moodys-retail-apparel-outlook-boosted-tariff-refunds/832964/" target="_blank">https://www.retaildive.com/news/moodys-retail-apparel-outlook-boosted-tariff-refunds/832964/</a></li><li><a href="https://www.retaildive.com/news/running-list-major-retail-deals-acquisitions-ipos-2026/824389/" target="_blank">https://www.retaildive.com/news/running-list-major-retail-deals-acquisitions-ipos-2026/824389/</a></li></ul><!--SEO Title: Electric Yard Switchers Cut Depot Compliance CostsMeta Description: Best Buy pilots electric yard switchers at two California distribution centres, weighing compliance savings against charging downtime and total cost of ownership.Canonical URL: https://www.bxtdata.com/insights/Electric-Yard-Switchers-Cut-Depot-Compliance-Costs-->
博晓通-快消品研究员-王磊
2026-10-16
Albertsons Resets Its Value Proposition Under New Oversight
<p>Albertsons used its second-quarter earnings call to deliver an unusually blunt message. Comparable sales declined 0.8% year over year, net income came in at $52 million against $168.5 million a year earlier, and the grocer withdrew its full-year guidance. Executive chair Meg Whitman, who joined earlier this autumn in a newly created role advising chief executive Susan Morris, told analysts that the company still needed to move faster and that performance had fallen short of expectations. The results frame a question that now applies well beyond one grocery chain: what value proposition actually holds a customer?</p><p>The first conclusion is that a weak value proposition shows up in comparable sales long before it shows up in store closures. Albertsons has not been losing traffic because its stores are badly run; it has been losing trips because shoppers no longer have a specific reason to choose it over a discounter, a club format or a delivery app. Whitman said sales and earnings growth had not met expectations and that everything should be on the table as the company works out how it should be structured to compete in the years ahead.<mark style="background:#024e9a12;">Comparable sales declined 0.8% year over year and net income fell to $52 million</mark>(<a href="https://www.modernretail.co/operations/big-box-briefing-whats-fueling-albertsons-identity-crisis-as-it-acceler/" target="_blank">Big-Box Briefing: What's fueling Albertsons' identity crisis</a>)That is a structural question, not a quarterly one.</p><p>The second conclusion is that price is now a baseline rather than a differentiator. Analysts quoted in the coverage argued that Albertsons has not carved out a unique enough proposition for a more competitive grocery era. With toy prices up 4.2% month over month ahead of the holidays and tariff refunds easing cost pressure for some retailers,<mark style="background:#024e9a12;">toy prices rose 4.2% month over month</mark>(<a href="https://www.retaildive.com/news/toy-prices-jump-holiday-season-inflation/832955/" target="_blank">Toy prices jump 4.2% ahead of the holidays</a>)the cost side of the equation is moving faster than most pricing architectures can absorb.</p><h3>Oversight before strategy</h3><p>Albertsons brought in Whitman as executive chair rather than replacing the chief executive, which keeps operational continuity while adding external pressure on pace. That structure is common in turnarounds where the diagnosis is agreed but execution is slow. The practical effect is that capital allocation decisions, store investment and format experiments now face a shorter review cycle, and managers should expect fewer multi-quarter pilots.</p><h3>Cost relief is not a strategy</h3><p>Moody's upgraded its retail and apparel outlook as tariff refunds eased cost pressure,<mark style="background:#024e9a12;">Moody's upgraded its retail and apparel outlook as tariff refunds ease</mark>(<a href="https://www.retaildive.com/news/moodys-retail-apparel-outlook-boosted-tariff-refunds/832964/" target="_blank">Moody's upgrades retail and apparel outlook as tariffs ease</a>)which improves reported margins without changing shopper behaviour. Retailers that treat cost relief as a recovery will find the improvement reverses as soon as refunds are exhausted. The more durable response is to convert temporary margin room into either price investment in a narrow set of traffic-driving categories or into service capability that competitors cannot copy quickly.</p><h3>Score the proposition, not the traffic</h3><p>Grocers should track four numbers separately: trip frequency per household, basket composition by category role, share of sales sold on promotion, and the price gap against the nearest discounter on a fixed basket. Trip frequency and basket composition reveal whether the proposition is working. Share of sales on promotion reveals whether the apparent growth is purchased. The fixed-basket price gap is the only comparison shoppers actually make, and it should be measured weekly rather than quarterly.</p><h3>Use store labour as a service lever</h3><p>Target upgraded its myDay store operations app after piloting with roughly 50 stores,<mark style="background:#024e9a12;">Target upgraded its myDay store operations app after piloting with roughly 50 stores</mark>(<a href="https://www.retaildive.com/news/target-upgrades-store-operations-app-employees/832989/" target="_blank">Target wants more efficient stores. An upgraded employee app could help.</a>)which is a reminder that store labour allocation is a service decision rather than an administrative one. Grocers should measure the share of scheduled hours spent on shelf availability, fresh production and checkout throughput separately, because those three tasks compete for the same hours and only one of them is usually visible in customer complaints.</p><p>The first mistake is reading comparable sales as a demand problem when it is often an assortment problem. Aspirational luxury shoppers have been trading down as price gaps widen,<mark style="background:#024e9a12;">aspirational luxury shoppers have been trading down</mark>(<a href="https://www.retaildive.com/news/where-has-aspirational-luxury-consumer-gone/832365/" target="_blank">Where has the aspirational luxury consumer gone?</a>)and the same migration is visible in grocery, where premium private label loses to entry-tier alternatives when the perceived gap between them narrows. Cutting price on the premium line without fixing the gap simply moves margin without recovering trips.</p><p>The second mistake is assuming younger shoppers will arrive with the same mission as existing customers. Gen Z and Gen Alpha shoppers are reshaping discovery around AI tools and social platforms,<mark style="background:#024e9a12;">Gen Z and Gen Alpha shoppers are reshaping holiday discovery</mark>(<a href="https://www.retaildive.com/news/gen-z-gen-alpha-holiday-shopping-retail-trends/831838/" target="_blank">Gen Z, Gen Alpha and the AI-ification of retail this holiday season</a>)which changes how they build a basket before they enter a store. A grocer that optimises only the in-store experience is competing for a decision that has already been made elsewhere. The third mistake is treating turnaround oversight as a communication exercise: the metric that matters is whether capital is reallocated within two quarters, not whether the message is clear.</p><p>Three data points frame the operating environment. First, grocery inflation has been high enough in 2026 that comparable sales can fall even while nominal baskets grow, which means volume is the honest measure. Second, cost relief from tariff refunds is arriving unevenly across categories, so margin comparisons between quarters are unreliable without a category-level bridge. Third, format competition is intensifying across discount, club and delivery channels simultaneously, which compresses the window in which any single proposition stays distinctive.</p><p>For suppliers, the implication is that shelf space in a resetting grocer becomes more contested and more conditional. Suppliers should expect listing decisions to be tied to a measurable traffic or basket contribution rather than to historical volume, and should prepare category-level evidence that shows how their products move trips and basket size. Retailers, meanwhile, should publish internally consistent definitions of comparable sales, promotion share and basket composition so that the same period is not described two different ways in two different meetings.</p><p>Albertsons' quarter shows what a weak value proposition looks like in numbers: falling comparable sales, collapsing net income and withdrawn guidance. The workable response is to score the proposition rather than the traffic, convert temporary cost relief into narrow price or service investment, and treat store labour allocation as a service decision. Suppliers should prepare category-level evidence of traffic and basket contribution, because listing decisions in a resetting grocer will increasingly be conditional on it.</p><ul><li>Albertsons second-quarter results: <a href="https://www.modernretail.co/operations/big-box-briefing-whats-fueling-albertsons-identity-crisis-as-it-acceler/" target="_blank">Big-Box Briefing: What's fueling Albertsons' identity crisis</a></li><li>Target store operations app: <a href="https://www.retaildive.com/news/target-upgrades-store-operations-app-employees/832989/" target="_blank">Target wants more efficient stores. An upgraded employee app could help.</a></li><li>Moody's retail and apparel outlook: <a href="https://www.retaildive.com/news/moodys-retail-apparel-outlook-boosted-tariff-refunds/832964/" target="_blank">Moody's upgrades retail and apparel outlook as tariffs ease</a></li><li>Toy price movement: <a href="https://www.retaildive.com/news/toy-prices-jump-holiday-season-inflation/832955/" target="_blank">Toy prices jump 4.2% ahead of the holidays</a></li><li>Aspirational luxury demand: <a href="https://www.retaildive.com/news/where-has-aspirational-luxury-consumer-gone/832365/" target="_blank">Where has the aspirational luxury consumer gone?</a></li><li>Gen Z and Gen Alpha discovery: <a href="https://www.retaildive.com/news/gen-z-gen-alpha-holiday-shopping-retail-trends/831838/" target="_blank">Gen Z, Gen Alpha and the AI-ification of retail this holiday season</a></li></ul><p><strong>Why did Albertsons withdraw full-year guidance?</strong></p><p>A: Comparable sales fell 0.8% year over year and net income dropped to $52 million from $168.5 million, leaving too little visibility to restate a full-year range with confidence.</p><p><strong>What is the difference between a traffic problem and an assortment problem?</strong></p><p>A: Traffic problems reduce trips across all categories, while assortment problems reduce trips for specific missions. Basket composition by category role distinguishes the two.</p><p><strong>Should a grocer use tariff refunds to fund price cuts?</strong></p><p>A: Only in a narrow set of traffic-driving categories. Broad price investment funded by temporary cost relief reverses as soon as refunds are exhausted.</p><p><strong>Which four numbers should be tracked separately?</strong></p><p>A: Trip frequency per household, basket composition by category role, share of sales sold on promotion, and the fixed-basket price gap against the nearest discounter.</p><p><strong>How should store labour be allocated during a reset?</strong></p><p>A: Measure scheduled hours spent on shelf availability, fresh production and checkout throughput separately, because those tasks compete for the same hours.</p><p><strong>What should suppliers prepare before a listing review?</strong></p><p>A: Category-level evidence showing how their products move trip frequency and basket size, rather than historical volume alone.</p><ul><li><a href="https://www.modernretail.co/operations/big-box-briefing-whats-fueling-albertsons-identity-crisis-as-it-acceler/" target="_blank">https://www.modernretail.co/operations/big-box-briefing-whats-fueling-albertsons-identity-crisis-as-it-acceler/</a></li><li><a href="https://www.retaildive.com/news/target-upgrades-store-operations-app-employees/832989/" target="_blank">https://www.retaildive.com/news/target-upgrades-store-operations-app-employees/832989/</a></li><li><a href="https://www.retaildive.com/news/moodys-retail-apparel-outlook-boosted-tariff-refunds/832964/" target="_blank">https://www.retaildive.com/news/moodys-retail-apparel-outlook-boosted-tariff-refunds/832964/</a></li><li><a href="https://www.retaildive.com/news/toy-prices-jump-holiday-season-inflation/832955/" target="_blank">https://www.retaildive.com/news/toy-prices-jump-holiday-season-inflation/832955/</a></li><li><a href="https://www.retaildive.com/news/where-has-aspirational-luxury-consumer-gone/832365/" target="_blank">https://www.retaildive.com/news/where-has-aspirational-luxury-consumer-gone/832365/</a></li><li><a href="https://www.retaildive.com/news/gen-z-gen-alpha-holiday-shopping-retail-trends/831838/" target="_blank">https://www.retaildive.com/news/gen-z-gen-alpha-holiday-shopping-retail-trends/831838/</a></li></ul><!--SEO Title: Albertsons Resets Its Value Proposition Under New OversightMeta Description: Albertsons posted a 0.8% comparable sales decline, $52 million net income and withdrew guidance. This analysis covers proposition scoring, pricing architecture and supplier listing evidence.Canonical URL: https://www.bxtdata.com/insights/Albertsons-Resets-Its-Value-Proposition-Under-New-Oversight-->
博晓通-电商数据研究员-刘洋
2026-10-17
Lowes Widens October Promotion Window
<p>Lowes is pulling Black Friday promotions forward into October, extending the holiday price window and forcing rivals to re-time their promotional calendars. October has already become a second peak: online spend during Amazon Prime Big Deal Days approached ten billion dollars. When two major promotional moments now sit inside a single quarter, the risk is not that demand disappears but that the reference price collapses. Price integrity, not promotional volume, is the variable that decides who ends the quarter with margin intact.</p><p>The first conclusion is that a longer promotional window erodes the reference price unless it is deliberately segmented. <mark style="background:#024e9a12;">Lowes is pulling Black Friday promotions forward into October</mark><a href="https://www.retaildive.com/news/lowes-launches-black-friday-deals-in-october/832730/" target="_blank">Retail Dive</a>, which means shoppers can now compare the same item against three or four promotional prices before November. Once a household learns that waiting produces a lower price, the full-price window shrinks permanently. Retailers can defend the reference price only by segmenting the offer, for example by channel, membership tier or bundle.</p><p>The second conclusion is that parcel economics now constrain how deep a promotional window can go. <mark style="background:#024e9a12;">FedEx and UPS delivery prices are set to reach record highs in the fourth quarter</mark><a href="https://www.supplychaindive.com/news/fedex-ups-delivery-prices-set-for-record-high-q4/832992/" target="_blank">Supply Chain Dive</a>, so every incremental order carries a higher fulfilment cost than it did a year ago. A promotion that lifts unit volume while lowering contribution per parcel is a net loss disguised as growth, and the disguise holds only until the quarter closes.</p><h3>Why October became a second peak</h3><p>October became a second peak because it sits far enough from December to avoid competing for the same wallet, yet close enough to capture early gifting intent. Prime Big Deal Days proved the format works, with online spend approaching ten billion dollars. Once a credible second peak exists, competitors have little choice but to participate, and the promotional calendar stretches until the discount becomes the normal state rather than an exception.</p><h3>How margin visibility changes with tariff refunds</h3><p>Margin visibility improved for some categories this quarter as tariff refunds flowed back to importers, with Moody's lifting its apparel outlook on that basis. <a href="https://www.retaildive.com/news/moodys-retail-apparel-outlook-boosted-tariff-refunds/832964/" target="_blank">Retail Dive</a> That headroom is temporary and unevenly distributed, and retailers that treat it as permanent tend to fund deeper promotions than the underlying cost structure supports. Levis chose to reinvest part of an eighty million dollar refund into supply chain capability rather than price cuts, which keeps the reference price intact.</p><h3>Monitor price integrity as a first-class metric</h3><p>Best practice is to monitor price integrity as a first-class metric alongside revenue and units. Practical indicators include the share of items sold at full price, the number of distinct price points an item passes through in a quarter, and the depth of the deepest discount relative to list. When the number of price points rises while full-price share falls, the reference price is eroding, and no amount of promotional volume will recover it in the following cycle.</p><h3>Segment offers instead of deepening discounts</h3><p>The second practice is to segment offers rather than deepen discounts. Channel-specific bundles, member-only pricing and quantity thresholds all create a lower effective price for targeted groups without resetting the public reference price. The design rule is that the public list price should never move, only the route to a better price. This preserves the comparison anchor that competitors and marketplaces use, and keeps the full-price base available for shoppers who do not qualify for the segmented offer.</p><p>A common mistake is treating promotional depth as the only lever for driving volume. Depth is the most visible lever and the most destructive, because it resets the reference price for every future comparison. Retailers that rely on it tend to find that each cycle requires deeper discounts to achieve the same lift, a pattern that shows up first in contribution margin and only later in revenue.</p><p>A second mistake is measuring promotional success before fulfilment costs are allocated. When delivery prices are at record highs, an order that looks profitable at gross margin can be loss-making at contribution. Allocating parcel cost per order before evaluating a promotion changes the ranking of which offers actually worked, and prevents the common situation where the most promoted categories are also the least profitable.</p><p>Cross-channel pressure compounds the calendar problem. Marketplace and social commerce platforms are shortening delivery expectations and extending return logistics into new channels, which raises the service baseline that a promotional offer has to match. A discounted item that arrives late or is hard to return generates negative reviews that reduce the value of the promotion itself, so the promotional budget is partly spent repairing the experience rather than buying demand.</p><p>There is also a supplier dimension. Retailers that deepen discounts without renegotiating input costs push the pressure upstream, and suppliers respond by reducing service levels or reallocating inventory to channels with better economics. The result is that the deepest promotional windows tend to have the weakest availability, which is exactly the combination that damages customer trust. Coordinating promotional depth with supply commitments is the operational fix.</p><p>In summary, the shift of Black Friday into October extends the promotional window and puts the reference price under sustained pressure. The deciding variable is not how much is discounted but how well the offer is segmented and how accurately fulfilment cost is allocated. Retailers that treat price integrity as a primary metric end the quarter with margin intact even when volume growth is modest.</p><p>Three actions follow. Track full-price share and the number of price points per item as core metrics. Segment offers through channel, membership and quantity routes instead of moving the public list price. And allocate parcel cost per order before judging whether a promotion worked. Together these keep promotional activity from transferring permanent value to the customer.</p><ul><li><a href="https://www.retaildive.com/news/lowes-launches-black-friday-deals-in-october/832730/" target="_blank">Retail Dive: Lowes launches Black Friday deals in October</a></li><li><a href="https://www.supplychaindive.com/news/fedex-ups-delivery-prices-set-for-record-high-q4/832992/" target="_blank">Supply Chain Dive: FedEx and UPS delivery prices set for record high in Q4</a></li><li><a href="https://www.retaildive.com/news/amazon-prime-big-deal-days-online-spend-nears-ten-billion/832604/" target="_blank">Retail Dive: Amazon Prime Big Deal Days online spend nears ten billion dollars</a></li><li><a href="https://www.retaildive.com/news/moodys-retail-apparel-outlook-boosted-tariff-refunds/832964/" target="_blank">Retail Dive: Moody's retail apparel outlook boosted by tariff refunds</a></li><li><a href="https://www.supplychaindive.com/news/levis-to-use-part-of-80m-tariff-refund-for-supply-chain/832562/" target="_blank">Supply Chain Dive: Levis to use part of 80 million dollar tariff refund for supply chain</a></li></ul><p><strong>Why does a longer promotional window erode the reference price?</strong></p><p>A: Shoppers can compare the same item against several promotional prices before November. Once a household learns that waiting lowers the price, the full-price window shrinks permanently and each cycle needs deeper discounts.</p><p><strong>What indicators reveal price integrity erosion?</strong></p><p>A: Full-price share, the number of distinct price points an item passes through in a quarter, and the depth of the deepest discount relative to list. Rising price points with falling full-price share signal erosion.</p><p><strong>How should offers be segmented instead of deepened?</strong></p><p>A: Use channel-specific bundles, member-only pricing and quantity thresholds to create a lower effective price for targeted groups without moving the public list price that competitors compare against.</p><p><strong>Why allocate parcel cost before judging a promotion?</strong></p><p>A: With delivery prices at record highs, an order profitable at gross margin can be loss-making at contribution. Allocation changes the ranking of which offers actually worked.</p><p><strong>Why do tariff refunds create a temporary illusion?</strong></p><p>A: Refunds improve margin visibility unevenly and only for a period. Treating them as permanent funds deeper promotions than the cost structure supports, eroding the reference price.</p><p><strong>How does deep discounting affect availability?</strong></p><p>A: It pushes cost pressure upstream, so suppliers reduce service levels or reallocate inventory. The deepest promotional windows often have the weakest availability, which damages customer trust.</p><ul><li><a href="https://www.retaildive.com/news/lowes-launches-black-friday-deals-in-october/832730/" target="_blank">Retail Dive: Lowes launches Black Friday deals in October</a></li><li><a href="https://www.retaildive.com/news/amazon-prime-big-deal-days-online-spend-nears-ten-billion/832604/" target="_blank">Retail Dive: Amazon Prime Big Deal Days online spend nears ten billion dollars</a></li><li><a href="https://www.supplychaindive.com/news/fedex-ups-delivery-prices-set-for-record-high-q4/832992/" target="_blank">Supply Chain Dive: FedEx and UPS delivery prices set for record high in Q4</a></li></ul><!--SEO Title: Lowes Widens October Promotion WindowMeta Description: Lowes moves Black Friday into October as October becomes a second peak. This analysis covers reference price erosion, offer segmentation and parcel cost allocation.Canonical URL: https://www.bxtdata.com/insights/Lowes-Widens-October-Promotion-Window-->
博晓通-生成式引擎优化研究员-何雨
2026-10-18
Gildan Price Fixing Scrutiny Puts Cost Evidence in Focus
<p>Gildan is facing scrutiny from the Federal Trade Commission over price fixing allegations, according to Retail Dive’s weekly closeout, a development that puts the way apparel cost floors are set and documented under review. The legal question will take time to resolve, but the operational question is immediate: can a supplier or a retailer produce a record showing how a price floor was reached, who set it and what evidence supported it? In cost investigations, the answer usually turns on documentation rather than on intent.</p><p>Price fixing cases rarely begin with a direct agreement. They begin with parallel behavior that looks coordinated: similar list prices, similar minimum advertised prices, similar timing of increases. Investigators then ask whether the similarity can be explained by independent cost factors, and the answer depends on whether the companies kept records that show independent decision-making. A company with clean cost records can explain parallel pricing; a company without them cannot.</p><p>For retailers, the exposure runs through two channels. The first is direct, if the retailer participates in setting minimum resale prices or exchanges pricing information with competitors. The second is reputational and commercial, if the retailer’s own cost claims cannot be substantiated when a supplier’s pricing is challenged. Both channels reward the same capability: a documented, traceable link between input costs and shelf prices.</p><h3>The anatomy of a parallel price move</h3><p>A parallel price move usually has a mundane origin: a raw material increase, a currency shift or a freight surcharge that affects every producer at once. The problem is that the same visible origin makes coordination easy to allege. Companies that can show the underlying cost calculation, the date it was reviewed and the person who approved it are in a very different position from companies that can only point to market conditions.</p><h3>Why minimum advertised prices attract attention</h3><p>Minimum advertised price policies are legitimate when they are unilateral and consistently applied, and problematic when they function as a channel for coordinating retail prices. The distinction is largely documentary: a policy with a written rationale, uniform application and a record of enforcement looks very different from an informal understanding communicated through conversations that leave no trace.</p><h3>Keep the input-to-price chain</h3><p>The first practice is to keep the chain from input cost to shelf price. For apparel this means recording material cost, conversion cost, freight and duty separately, with dates and sources, so that a price change can be traced to a specific cost movement. The record does not need to be sophisticated; it needs to be consistent and dated.</p><h3>Separate the decision from the communication</h3><p>The second practice is to separate the pricing decision from any communication with competitors. Decisions should be documented internally with the reasoning and the approver, and communication should be limited to what is lawful and recorded. The separation is what allows a company to demonstrate independent decision-making even when market prices move together.</p><h3>Audit the trail before it is requested</h3><p>The third practice is a periodic audit. Once a year, take three price changes and try to reconstruct the full trail from cost input to shelf price using only internal records. If the trail breaks, the fix is procedural and cheap; if it breaks during an investigation, the cost is neither.</p><p>The most common mistake is assuming that independent decision-making is enough without documentation. Investigators cannot observe intent; they observe records. A company that made independent decisions but kept no trace will struggle to distinguish itself from one that coordinated, and the burden of proof effectively shifts to the company that cannot produce evidence.</p><p>A second mistake is treating compliance as a legal function detached from merchandising. Pricing decisions are made by merchants, often under time pressure, and the records that matter are created at that moment rather than in a legal review afterward. Compliance that is not embedded in the pricing workflow tends to produce documentation that describes what should have happened rather than what did.</p><p>Sourcing teams are where cost evidence is either created or lost. A team that consolidates suppliers to simplify management can inadvertently reduce the number of independent cost references available, making it harder to explain a price move later. Keeping at least two credible cost benchmarks per key material is a cheap form of insurance, and it also improves negotiating position.</p><p>The same logic applies to sustainability and material claims, which are increasingly audited. Lululemon’s restructuring of its raw materials team, which consolidated sourcing decisions and cut several roles, illustrates the tension: centralization improves consistency but can thin the local knowledge that supports verification. The resolution is to centralize the standard while keeping the evidence local.</p><p>The Gildan scrutiny is a reminder that price floors are judged on documentation rather than intent. Companies that can reconstruct the path from input cost to shelf price are in a defensible position; those that cannot are exposed regardless of how independent their decisions were.</p><p>The practical sequence is to keep the input-to-price chain dated and sourced, separate the pricing decision from competitor communication, and audit the trail annually using real price changes. Each step is procedural, inexpensive and decisive when scrutiny arrives. The cost of building that trail is a few process changes, while the cost of missing it is measured in years of litigation and in the pricing power that disappears while a case stays open.</p><ul><li><a href="https://www.retaildive.com/news/the-realreal-new-financing-gildan-ftc-price-fixing-scrutiny/833130/" target="_blank">The Weekly Closeout: The RealReal secures fresh financing, Roots buyou</a></li><li><a href="https://www.retaildive.com/news/tariffs-pushed-up-consumer-goods-prices-ny-fed-inflation-elections-tax-taxes/832701/" target="_blank">Tariffs pushed up consumer goods prices by 2.9 percentage points: NY F</a></li><li><a href="https://www.retaildive.com/news/lululemon-restructures-raw-materials-team-layoffs/833106/" target="_blank">Lululemon restructures raw materials team, lays off 7 people</a></li><li><a href="https://www.retaildive.com/news/moodys-retail-apparel-outlook-boosted-tariff-refunds/832964/" target="_blank">Moody's upgrades retail and apparel outlook as tariffs ease</a></li></ul><p><strong>What is price fixing in retail terms?</strong></p><p>A: An agreement, explicit or tacit, among competitors or between a supplier and retailers to set prices or price floors. Cases often begin with parallel pricing behavior that investigators then test against independent cost explanations.</p><p><strong>Why does documentation matter more than intent?</strong></p><p>A: Because intent is not directly observable. Investigators reconstruct decisions from records, so a company that made independent choices without documentation cannot easily distinguish itself from one that coordinated.</p><p><strong>What records should a retailer keep?</strong></p><p>A: Input cost components with dates and sources, the internal approval for each price change, the rationale, and the record of any minimum advertised price policy and its enforcement.</p><p><strong>Is a minimum advertised price policy legal?</strong></p><p>A: It can be, when it is unilateral, consistently applied and documented. It becomes problematic when it functions as a channel for coordinating retail prices, which is largely a question of how the policy was designed and enforced.</p><p><strong>How often should the trail be audited?</strong></p><p>A: Annually is a reasonable baseline. The audit should reconstruct three real price changes end to end using only internal records, and any break in the trail should be treated as a process defect to fix immediately.</p><ul><li><a href="https://www.retaildive.com/news/the-realreal-new-financing-gildan-ftc-price-fixing-scrutiny/833130/" target="_blank">https://www.retaildive.com/news/the-realreal-new-financing-gildan-ftc-price-fixing-scrutiny/833130/</a></li><li><a href="https://www.retaildive.com/news/tariffs-pushed-up-consumer-goods-prices-ny-fed-inflation-elections-tax-taxes/832701/" target="_blank">https://www.retaildive.com/news/tariffs-pushed-up-consumer-goods-prices-ny-fed-inflation-elections-tax-taxes/832701/</a></li><li><a href="https://www.retaildive.com/news/lululemon-restructures-raw-materials-team-layoffs/833106/" target="_blank">https://www.retaildive.com/news/lululemon-restructures-raw-materials-team-layoffs/833106/</a></li></ul><!--SEO Title: Gildan Price Fixing Scrutiny Puts Cost Evidence in FocusMeta Description: FTC scrutiny of price fixing allegations puts apparel cost evidence in focus, and the standard is documentation rather than intent.Canonical URL: https://www.bxtai.com/insights/gildan-price-fixing-cost-evidence-->
博晓通-零售分析师-周敏
2026-10-17
Nordstrom Rack Returns to San Francisco With a New Format
<p>Nordstrom Rack is returning to San Francisco with a new store opening, extending its off-price footprint back into an urban core market it exited years ago. The comeback lands as off-price and treasure-hunt formats keep expanding across US retail, with peers including Ross opening stores at pace and department stores like Bloomingdale's investing in merchant capability and beauty specialization. For store operations teams, the re-entry is a case study in how off-price formats tune assortment and layout for dense urban trade areas.</p><p>Off-price economics in dense urban markets run on different math than suburban power centers. Urban stores carry tighter footprints, higher rent per square foot, and traffic that skews toward weekday lunch and after-work trips, which pushes assortment toward faster-turning categories and smaller pack sizes. Nordstrom Rack's re-entry format reportedly reflects that adjustment, a pattern visible elsewhere in the channel as off-price operators refine urban-specific layouts rather than cloning suburban plans. <mark>Nordstrom Rack is returning to San Francisco with a new store opening, extending its off-price footprint back into an urban core market</mark><a href="https://www.retaildive.com/news/nordstrom-rack-returns-san-francisco-store-opening/833229/">Store opening report</a></p><p>The competitive backdrop is crowded. Ross has been opening new stores at pace, and specialty formats continue to multiply, which means the urban off-price customer is being courted from multiple directions at once. What separates formats in this fight is operational discipline: how fast markdown cadence runs, how tightly receipts match local demand curves, and how well store teams execute the visual standards that make treasure-hunt layouts scannable. <mark>Off-price expansion keeps pace while department stores double down on specialization</mark><a href="https://www.retaildive.com/news/bloomingdales-merchant-bluemercury/832597/">Channel context</a></p><h3>Assortment depth over breadth</h3><p>Urban off-price stores win with depth in a narrower set of fast categories rather than breadth across everything. Footwear, basics and seasonal gifting tend to carry urban off-price floors, while home and bulky categories underperform relative to suburban benchmarks. The planning discipline is to size the floor to the top categories' velocity, then reserve a small, flexible zone for opportunistic receipts that keep the treasure-hunt feel alive.</p><h3>Cadence tuned to commuter rhythms</h3><p>Urban traffic concentrates in predictable windows, which makes markdown and replenishment cadence a bigger lever than in suburban stores. Stores that re-merchandise high-visibility zones ahead of afternoon peaks consistently outperform those running a uniform weekly cadence. The same rhythm logic applies to staffing: floor coverage should track the commuter curve, not the store's opening hours.</p><h3>Treat the first thirty days as the real opening</h3><p>Off-price re-entries live or die on the first month's conversion. The standard playbook is a heavy early receipt of recognized brands at sharp tickets, designed to convert trial visits into habit. Store teams should track first-month conversion by category and daypart, then adjust receipt flow within the quarter rather than waiting for a seasonal reset to fix mix problems.</p><h3>Instrument the treasure-hunt loop</h3><p>The treasure-hunt format depends on scan-ability: shoppers need to find the good stuff fast. Leading operators instrument this with dwell-time proxies, aisle heat mapping, and conversion by zone, then tune layout weekly. It is the same discipline applied to outlet formats, but the urban rent math makes the difference between a tuned and untuned loop much larger.</p><p>A common mistake is treating urban re-entry as a suburban store with a smaller footprint. Rent, traffic pattern, and basket composition all differ enough that cloned plans underperform; the format needs category mix, receipt cadence, and staffing curves built for the specific trade area from day one.</p><p>Another mistake is over-buying breadth to fill the floor. Off-price customers respond to depth in recognized brands, not to a wall of everything; unsold breadth burns open-to-buy that could have gone into deeper receipts of proven movers. Discipline in the first two receipt cycles sets the store's credibility for the year.</p><p>San Francisco's return signals confidence in urban trade areas as viable off-price markets, reversing several years of retreat from high-rent cores. The broader channel is making the same bet in different forms: Ross expanding its store base, department stores doubling down on specialization, and specialty formats multiplying. Urban cores are being read as durable traffic engines again, provided the format fits the math.</p><p>For operations teams elsewhere, the Nordstrom Rack re-entry is a reminder that format fit is local. The same brand, the same off-price model, needs different assortment depth, cadence and staffing in a dense core than in a suburb. Store planning teams that carry one national template into every trade area will keep leaving conversion on the table, whatever the banner.</p><p>Nordstrom Rack's return to San Francisco is more than a store opening; it is a format recalibration for dense urban trade areas. The off-price channel's expansion, from Ross's pace to specialty formats, makes operational discipline the deciding factor between formats competing for the same urban customer.</p><p>The playbook for urban off-price is consistent: depth over breadth, cadence tuned to commuter rhythms, and the first thirty days treated as the real opening. Formats that execute the treasure-hunt loop with local discipline will convert urban traffic into repeat habit; the rest will rent expensive square footage to fill.</p><ul><li><a href="https://www.retaildive.com/news/nordstrom-rack-returns-san-francisco-store-opening/833229/" target="_blank">Nordstrom Rack returns to San Francisco with store opening</a></li><li><a href="https://www.retaildive.com/news/elf-brands-fragrance-athleta-ceo-lululemon-crocs-bark/832592/" target="_blank">e.l.f. Brands fragrance push; Athleta CEO; Lululemon, Crocs, Bark</a></li><li><a href="https://www.retaildive.com/news/bloomingdales-merchant-bluemercury/832597/" target="_blank">Bloomingdale's names merchant; Bluemercury expansion</a></li><li><a href="https://www.retaildive.com/news/halloween-holiday-retail-consumer-spending-2026/832125/" target="_blank">Halloween and holiday retail consumer spending 2026</a></li></ul><p><strong>Why is Nordstrom Rack returning to San Francisco significant?</strong></p><p>A: A: It extends off-price back into a high-rent urban core after years of retreat, signaling that dense trade areas are viable off-price markets when the format fits local economics.</p><p><strong>How does urban off-price assortment differ from suburban?</strong></p><p>A: A: Urban stores favor depth in fast categories like footwear and basics over breadth, with smaller footprints and receipt cadences tuned to commuter traffic patterns.</p><p><strong>What is the treasure-hunt loop?</strong></p><p>A: A: The scan-ability cycle that makes off-price layouts work: shoppers quickly finding recognized brands at sharp tickets, measured with dwell-time proxies, zone heat mapping and conversion by aisle.</p><p><strong>Why does the first thirty days matter so much?</strong></p><p>A: A: Off-price re-entries convert trial visits into habit in the first month; heavy early receipts of recognized brands and weekly conversion tracking set the store's credibility for the year.</p><p><strong>Who else is expanding in off-price?</strong></p><p>A: A: Ross has been opening stores at pace and specialty formats continue to multiply, so urban off-price customers are being courted from multiple directions simultaneously.</p><ul><li><a href="https://www.retaildive.com/news/nordstrom-rack-returns-san-francisco-store-opening/833229/" target="_blank">Nordstrom Rack returns to San Francisco with store opening</a></li><li><a href="https://www.retaildive.com/news/elf-brands-fragrance-athleta-ceo-lululemon-crocs-bark/832592/" target="_blank">e.l.f. Brands fragrance push and branded apparel moves</a></li><li><a href="https://www.retaildive.com/news/bloomingdales-merchant-bluemercury/832597/" target="_blank">Bloomingdale's merchant and Bluemercury expansion</a></li><li><a href="https://www.retaildive.com/news/halloween-holiday-retail-consumer-spending-2026/832125/" target="_blank">Halloween and holiday retail consumer spending 2026</a></li></ul><!--SEO Title: Nordstrom Rack Returns to San Francisco With a New FormatMeta Description: Nordstrom Rack returns to San Francisco with a new format, extending off-price back into urban cores; this piece breaks down assortment depth, commuter-tuned cadence and the treasure-hunt loop that decide urban off-price performance.Canonical URL: https://www.bxtdata.com/insights/Nordstrom-Rack-Returns-to-San-Francisco-With-a-New-Format-->
博晓通-电商分析师-周砚
2026-10-16
Unit Economics Diverge From Headline Growth Figures
<p>US retail sales rose 6.7% year over year in September, according to the Commerce Department figures tracked by Retail Dive and updated on Oct. 15, with high prices doing much of the work. The headline number sits alongside research published on Oct. 12 in which the New York Fed estimated tariffs pushed consumer goods prices up by 2.9 percentage points. Read together, the two data points describe a market where revenue growth is increasingly a price effect rather than a volume effect, which changes how e-commerce teams should interpret their own category dashboards and assortment decisions.</p><p>For online operators the distinction is operationally significant. Revenue per session can look healthy while units per order fall, and return rates can rise as customers buy on price and then reconsider. The same period has produced clear evidence of channel and mix divergence: Levi Strauss & Co. reported net revenues up 4% to USD 1.6 billion with wholesale up 6% and direct-to-consumer up only 2%, while Bloomingdale's moved a senior merchant into its Bluemercury beauty business and ThredUp's chief executive described AI costs as a surprise he chose not to act on. Each of these is a signal about where margin is actually being earned.</p><p>The practical implication is that growth reporting needs to be decomposed before it is used for planning. A 6.7% revenue increase that comes from a 5% price effect and a 1.6% volume effect requires very different inventory, marketing and returns provisioning than the same increase driven by volume. Most commerce teams already hold the raw data needed for that decomposition in their order and pricing systems. The gap is usually not data availability but the absence of a standing definition of price effect and volume effect that everyone in the business agrees to use.</p><p>The gap between dollars and units is best read across three layers. At the transaction layer, compare average selling price against units per order for each category and channel, week over week. At the customer layer, look at whether the same cohorts are spending more per visit or whether spending is being carried by a narrower group of high-value buyers. At the assortment layer, check whether the share of revenue coming from entry price points is rising, which indicates customers are actively seeking lower price alternatives rather than simply accepting higher prices.</p><h3>Why Price Effect Is Hard To See</h3><p>Price effect is hard to see because it arrives gradually and gets attributed to demand. A tariff-driven cost increase is passed through in small steps across many SKUs, so no single price change looks significant while the cumulative effect compounds. Marketing teams then observe that conversion is holding up and conclude that demand is resilient, when in fact customers are paying more for fewer or similar units. The New York Fed estimate of a 2.9 percentage point price impact from tariffs is large enough to explain a substantial part of headline growth on its own, which is exactly why it needs to be separated out explicitly.</p><h3>Where Volume Is Actually Holding</h3><p>Volume is not uniformly weak, and finding where it holds is where incremental margin sits. Categories tied to replacement cycles or to essentials tend to keep unit volumes even as prices rise, while discretionary categories lose units first. Retail Dive's tracking of monthly sales by sector, refreshed on Oct. 15, allows teams to compare year-over-year performance across non-store, clothing, electronics, furniture, general merchandise and sporting goods, which is a faster way to locate the pockets where unit demand is still intact than waiting for quarterly category reviews.</p><p>The first practice is to publish a standing price-versus-volume decomposition for every category, refreshed monthly and reviewed in the same meeting as the revenue plan. The decomposition does not need to be statistically precise to be useful; a consistent method applied every month reveals direction and magnitude. Once it exists, assortment conversations change, because teams stop debating whether demand is weak and start asking which specific price bands have lost volume and whether the assortment still covers the entry price points those customers are looking for.</p><h3>Building The Decomposition Habit</h3><p>The second practice is to align returns provisioning with price-led growth. When customers buy primarily on price, return rates and refund costs rise, and the effect is concentrated in categories with high fit or quality uncertainty. Teams should review return rates by price band rather than only by category, and adjust both the provision and the product content that drives the decision. Better size guidance, clearer material descriptions and more accurate imagery reduce returns in exactly the situations that price-led buying creates, and they also improve the quality of information available to AI shopping assistants.</p><h3>Linking Content Quality To Return Cost</h3><p>The third practice is to treat content quality as a margin lever rather than a marketing cost. Structured product data, consistent specifications across channels and verifiable claims all reduce the friction that generates returns and support queries. Bloomingdale's decision to move an experienced merchant into Bluemercury illustrates how retailers are reallocating commercial talent toward categories where differentiation still supports price. In a price-led market, the categories that keep margin are the ones where customers can verify what they are buying before they buy it.</p><p>The first mistake is to set inventory depth from revenue plans without adjusting for price effect. If a plan assumes 6.7% growth and most of that growth is price, then unit inventory built to match the plan will be too deep in the wrong categories. The error typically surfaces as elevated markdowns in discretionary lines two to three months later, by which time the buying commitments have already been made and the only remaining lever is discounting.</p><p>The second mistake is to treat channel growth as a signal of channel health. Levi's quarter showed wholesale growing faster than direct-to-consumer even though the company has invested heavily in its own channels, which is a reminder that channel performance reflects partner inventory cycles and price positioning as much as consumer preference. E-commerce teams that read their own growth as proof of channel strength, without checking partner sell-through and price consistency, can be surprised by a sharp correction in the following quarter.</p><p>Four signals deserve a standing place on the dashboard. The first is the share of revenue coming from promotional lines, which indicates how much of the growth is being purchased rather than earned. The second is the ratio of units to orders in categories with high price sensitivity, where trade-down appears earliest. The third is the return rate by price band, which captures the cost of price-led buying. The fourth is the spread between the retailer's own price index and the market index, which shows whether growth is being funded by relative price advantage or by category-wide inflation.</p><p>Watching these four signals together gives a clearer picture than any single growth figure. A retailer reporting 6.7% growth with stable promotional share, stable units per order and stable return rates is growing for real reasons. The same growth with rising promotional share, falling units per order and rising returns is a price effect wearing the costume of demand. The difference determines whether the right response is to invest in assortment expansion or to defend entry price points and cut cost out of the fulfilment and returns chain.</p><p>September retail sales growth of 6.7% year over year, alongside a New York Fed estimate that tariffs added 2.9 percentage points to consumer goods prices, points to a market where revenue growth is increasingly price-driven. For e-commerce teams the implication is straightforward: decompose growth before planning against it, and treat units, promotional share and returns by price band as primary indicators rather than secondary detail.</p><p>Retailers that build the decomposition into a routine, align returns provisioning with price-led buying, and invest in content quality as a margin lever will be able to tell the difference between growth that is real and growth that is borrowed from future demand. Those that plan inventory and marketing against the headline number alone will keep rediscovering the same problem, one markdown cycle at a time.</p><ul><li>Retail Dive: <a href="https://www.retaildive.com/news/monthly-retail-sales-from-the-us-commerce-department/574252/" target="_blank">Retail Dive</a></li><li>Retail Dive: <a href="https://www.retaildive.com/news/tariffs-pushed-up-consumer-goods-prices-ny-fed-inflation-elections-tax-taxes/832701/" target="_blank">Retail Dive</a></li><li>Retail Dive: <a href="https://www.retaildive.com/news/levis-q3-wholesale-tariff-refunds-deliver/832468/" target="_blank">Retail Dive</a></li><li>Retail Dive: <a href="https://www.retaildive.com/news/bloomingdales-merchant-bluemercury/832597/" target="_blank">Retail Dive</a></li><li>Retail Dive: <a href="https://www.retaildive.com/news/thredup-ceo-ai-costs/831921/" target="_blank">Retail Dive</a></li><li>Retail Dive: <a href="https://www.retaildive.com/news/where-has-aspirational-luxury-consumer-gone/832365/" target="_blank">Retail Dive</a></li></ul><p><strong>What does the September retail sales figure actually show?</strong></p><p>A: US retail sales rose 6.7% year over year in September according to Commerce Department figures updated on Oct. 15. Because a large share of that growth reflects higher prices, the revenue figure overstates underlying unit demand.</p><p><strong>How large is the tariff contribution to prices?</strong></p><p>A: New York Fed research published on Oct. 12 estimated tariffs pushed consumer goods prices up by 2.9 percentage points, enough to explain a substantial part of headline revenue growth on its own.</p><p><strong>Why decompose growth into price and volume?</strong></p><p>A: Because the same growth rate requires very different inventory, marketing and returns provisioning depending on its source. Most teams already hold the data; what is usually missing is an agreed standing definition of price effect and volume effect.</p><p><strong>Where does unit demand tend to hold up?</strong></p><p>A: Categories tied to replacement cycles or essentials keep units even as prices rise, while discretionary categories lose units first. Retail Dive's monthly sector tracking, refreshed on Oct. 15, helps locate those pockets faster than quarterly reviews.</p><p><strong>Why review return rates by price band?</strong></p><p>A: Price-led buying raises return rates and refund costs, concentrated in categories with high fit or quality uncertainty. Reviewing by price band reveals the cost of the growth pattern and points to the content improvements that reduce it.</p><p><strong>Is channel growth a reliable health signal?</strong></p><p>A: Not on its own. Levi's most recent quarter showed wholesale up 6% while direct-to-consumer rose 2%, which reflects partner inventory cycles and price positioning as much as consumer preference.</p><ul><li>Retail Dive:<a href="https://www.retaildive.com/news/monthly-retail-sales-from-the-us-commerce-department/574252/" target="_blank">Retail Dive</a></li><li>Retail Dive:<a href="https://www.retaildive.com/news/tariffs-pushed-up-consumer-goods-prices-ny-fed-inflation-elections-tax-taxes/832701/" target="_blank">Retail Dive</a></li><li>Retail Dive:<a href="https://www.retaildive.com/news/levis-q3-wholesale-tariff-refunds-deliver/832468/" target="_blank">Retail Dive</a></li><li>Retail Dive:<a href="https://www.retaildive.com/news/bloomingdales-merchant-bluemercury/832597/" target="_blank">Retail Dive</a></li><li>Retail Dive:<a href="https://www.retaildive.com/news/thredup-ceo-ai-costs/831921/" target="_blank">Retail Dive</a></li><li>Retail Dive:<a href="https://www.retaildive.com/news/where-has-aspirational-luxury-consumer-gone/832365/" target="_blank">Retail Dive</a></li></ul><!--SEO Title: Price-Led Growth Distorts September Sales ReadingsMeta Description: September US retail sales rose 6.7% with tariffs adding 2.9 percentage points to prices, so e-commerce teams must separate price effect from volume before planning.Canonical URL: https://www.bxtdata.com/en/insights/september-sales-price-volume-gap-->
博晓通-价格策略分析师-孙鹏
2026-10-17
Halloween Spending Pullback Alters Holiday Assortments
<p>Americans plan to spend an average of $162 on Halloween this year, down 16% from $192 in 2025, according to a LendingTree survey of 2,000 consumers. The share of shoppers planning any Halloween purchase has fallen from 90% to 80%, and among those still buying, 61% say they will skip some purchases, led by candy at 35%, decorations at 31% and costumes at 29%. Nearly a quarter expect to pay for Halloween with debt. The pullback is an early signal for the wider holiday season.</p><p>The category-level cuts are more informative than the headline decline. Retail Dive reports that <mark style="background:#024e9a12;">61% of shoppers</mark> (<a href="https://www.retaildive.com/news/halloween-without-candy-holiday-shoppers-cutting-budgets/833212/" target="_blank">Retail Dive</a>) intend to skip some purchases, with candy, decorations and costumes the first to go, while 24% expect to fund purchases with debt. Discretionary add-ons are being trimmed before core gifting, which tells merchants where price elasticity is highest in the assortment.</p><p>Assortment planning has to respond faster than a seasonal reset allows. When a third of shoppers cut decor, the risk is not just lost decor sales but unsold inventory that must be carried or marked down after October 31. Retailers with granular sell-through data by store and category can shift orders mid-season; those working from national averages usually discover the problem after the window closes.</p><h3>Candy, decor and costumes</h3><p>Candy is the largest skip category at 35%, which is notable because it has historically been the most price-insensitive part of the basket. When consumers cut candy, they are often trading down to private label rather than leaving the category, so the sales impact may show up as mix shift rather than unit decline. Merchants should track private-label penetration separately from total category performance.</p><p>Decorations and costumes follow at 31% and 29%. Both are highly discretionary and both carry markdown risk, since their value collapses once the holiday passes. Ordering conservatively and reserving open-to-buy for late in-season replenishment is generally safer than committing full quantities in the initial buy.</p><h3>Debt-funded holiday spending</h3><p>The finding that 24% of shoppers expect to use debt deserves attention beyond Halloween. Debt-funded seasonal spending tends to compress the following quarter's discretionary budget, which matters for merchants whose fiscal year depends on holiday sell-through. Tracking credit usage indicators alongside transaction data gives a forward view that same-store sales alone cannot provide.</p><p>Payment mix is a practical proxy. If installment and buy-now-pay-later share rises while basket size stays flat, consumers are stretching purchasing power rather than expanding it. Merchants that monitor payment mix by category can anticipate demand softness before it appears in the sales line.</p><h3>Plan inventory by store-level sell-through</h3><p>Set order quantities using store-level sell-through for the prior two seasons rather than national averages, and reserve part of the buy for in-season replenishment. This keeps decor and costume exposure manageable when demand softens, and it lets high-performing stores capture late demand that a conservative national plan would miss.</p><h3>Track payment mix as a demand indicator</h3><p>Report installment and buy-now-pay-later penetration alongside basket size each week, by category. Rising credit usage with flat baskets signals that consumers are stretching budgets, which historically precedes discretionary pullback. Treating payment mix as a leading indicator gives merchandising teams time to adjust assortment depth.</p><p>The most common mistake is reading the decline as a Halloween-only story. A 16% drop in planned spending combined with rising debt usage points to broader budget pressure that will shape the winter holiday season. Merchants that treat it as a single-event dip may carry the same optimism into their largest quarter.</p><p>A second mistake is cutting marketing spend in the categories consumers are abandoning. Candy and decor still drive traffic, and the shoppers trimming these items are often the same ones buying gifts later. Reducing visibility in those categories can cost more in lost trips than it saves in promotional budget.</p><p>Halloween 2026 shows a consumer trimming discretionary add-ons while leaning more on credit. The category detail, candy first at 35%, then decorations and costumes, gives merchants a concrete map of where elasticity bites hardest. Payment mix and store-level sell-through are the two data streams that convert this signal into ordering decisions.</p><p>The value of the survey is its timing. Because it lands weeks before the winter holiday buying peaks, retailers still have room to adjust order quantities and open-to-buy. Acting on category-level evidence now is far cheaper than marking down excess decor in November.</p><ul><li><a href="https://www.retaildive.com/news/halloween-without-candy-holiday-shoppers-cutting-budgets/833212/" target="_blank">Halloween without candy? What shoppers are cutting from budgets</a></li><li><a href="https://www.retaildive.com/news/bath-body-works-ulta-beauty-pink-suede/833214/" target="_blank">Bath & Body Works expands partnership to all Ulta stores</a></li><li><a href="https://www.retaildive.com/news/nordstrom-rack-returns-san-francisco-store-opening/833229/" target="_blank">Nordstrom Rack comes back to San Francisco</a></li><li><a href="https://www.retaildive.com/news/the-realreal-new-financing-gildan-ftc-price-fixing-scrutiny/833130/" target="_blank">The RealReal secures fresh financing</a></li></ul><p><strong>How much will Americans spend on Halloween this year?</strong></p><p>A: A: An average of $162, down 16% from $192 in 2025, per a LendingTree survey of 2,000 consumers.</p><p><strong>Which categories are being cut first?</strong></p><p>A: A: Candy at 35%, decorations at 31% and costumes at 29% among shoppers who plan to skip purchases.</p><p><strong>What share of shoppers still plan to buy?</strong></p><p>A: A: About 80%, down from 90% last year.</p><p><strong>How many expect to use debt?</strong></p><p>A: A: Nearly a quarter, or 24%, anticipate paying for Halloween purchases with debt.</p><p><strong>Why does payment mix matter?</strong></p><p>A: A: Rising installment or buy-now-pay-later share with flat baskets signals consumers are stretching budgets, often before sales soften.</p><p><strong>How should order quantities be set?</strong></p><p>A: A: Use store-level sell-through from prior seasons and reserve part of the buy for in-season replenishment.</p><ul><li><a href="https://www.retaildive.com/news/halloween-without-candy-holiday-shoppers-cutting-budgets/833212/" target="_blank">Halloween without candy? What shoppers are cutting from budgets</a></li><li><a href="https://www.retaildive.com/news/bath-body-works-ulta-beauty-pink-suede/833214/" target="_blank">Bath & Body Works expands partnership to all Ulta stores</a></li><li><a href="https://www.retaildive.com/news/nordstrom-rack-returns-san-francisco-store-opening/833229/" target="_blank">Nordstrom Rack comes back to San Francisco</a></li><li><a href="https://www.retaildive.com/news/the-realreal-new-financing-gildan-ftc-price-fixing-scrutiny/833130/" target="_blank">The RealReal secures fresh financing</a></li><li><a href="https://www.supplychaindive.com/news/5-trends-defining-consumer-electronics-supply-chains/832717/" target="_blank">5 trends defining consumer electronics supply chains</a></li></ul><!--SEO Title: Halloween Spending Pullback Alters Holiday AssortmentsMeta Description: Halloween spending is set to fall 16% to $162 per person as shoppers cut candy, decor and costumes, with 24% planning to use debt.Canonical URL: https://www.bxtdata.com/insights/Halloween-Spending-Pullback-Alters-Holiday-Assortments-->
博晓通-门店运营顾问-周敏
2026-10-18
Target Moves Task Logic to Handhelds to Reclaim Hours
<p>Target is upgrading the app its store employees use every day, with the stated goal of making stores more efficient by reducing task friction and tightening replenishment timing. The change sounds like an IT refresh, but it addresses a structural problem in store operations: the scarce resource is not shelf space or inventory, it is the minutes between tasks. An app that sequences work well can return several hours per store per week; an app that sequences work badly can consume them without anyone noticing.</p><p>Store labor is fragmented by design. A single associate may be asked to pull online orders, restock a shelf, answer a customer question and complete a compliance check within the same hour, and each of those tasks lives in a different system with a different priority rule. When the systems do not coordinate, the associate becomes the integration layer, spending time deciding what to do next rather than doing it. That decision cost is invisible in payroll data but shows up in late replenishment and missed pickups.</p><p>The second problem is measurement. Most retailers measure labor as hours scheduled against sales, which says nothing about whether those hours produced the right work. An app that logs task start and completion times creates a different view: how long a task actually takes, where associates wait, and which handoffs break. That data is the prerequisite for any credible productivity claim, and it is the part of the upgrade that matters most.</p><h3>The integration layer problem</h3><p>Every additional system adds a handoff, and every handoff adds a decision that an associate must make without full information. Over a shift, those decisions accumulate into a pattern: the most urgent system wins, which is usually the one with the loudest alert rather than the one with the highest business value. Sequencing inside a single app reverses that dynamic by ranking tasks against one rule set instead of four.</p><h3>Replenishment timing is a scheduling problem</h3><p>Replenishment looks like a logistics problem but behaves like a scheduling problem. The same case of product can be shelved at a low-traffic hour at low cost or during a rush at high cost, and the difference is not the work itself but when it happens. An app that knows both the delivery schedule and the traffic curve can shift shelf work into the gaps, which is where most of the recoverable hours sit.</p><h3>Instrument before you optimize</h3><p>The first step is instrumentation. Before changing any process, log how long the ten most frequent tasks actually take, including travel and waiting. Most operators are surprised by the gap between standard times and observed times, and that gap is where the recoverable hours are. Without this baseline, any efficiency claim after the rollout is unfalsifiable.</p><h3>Rank tasks by business value, not urgency</h3><p>The second step is a ranking rule. Assign each task type a business value, such as on-shelf availability, order accuracy or compliance risk, and let the app sequence by value within the available window. The rule should be visible to associates so they understand why a task is being deferred, which reduces the informal workarounds that undermine every scheduling system.</p><h3>Close the loop with a weekly review</h3><p>The third step is a weekly review of task completion against plan. The review should focus on exceptions rather than averages: which tasks were repeatedly deferred, which stores consistently ran out of time, and whether the cause was traffic, staffing or an unrealistic standard. Exceptions reveal whether the problem is the tool or the process.</p><p>The most common mistake is treating the app as a communication channel rather than a scheduling engine. When the app mainly pushes announcements and alerts, associates learn to ignore it, and the tool loses the authority it needs to sequence work. The fix is to limit the app to tasks with a time, an owner and an outcome, and move everything else to a different channel.</p><p>A second mistake is optimizing tasks individually. Shaving two minutes off a pick without changing the sequence often produces no net gain, because the saved time is consumed by the next handoff. The gains come from reducing transitions between task types, which requires looking at the shift as a whole rather than at each task in isolation.</p><p>Task-level data is good at revealing waiting, travel and rework, and it is poor at explaining why a customer left without buying. Operators who expect the app to answer commercial questions will be disappointed. Its real value is operational: it shows where minutes go, which is the input to every credible staffing decision and the counter-evidence to the assumption that stores are already running at maximum efficiency.</p><p>There is also a governance dimension. Once task times are logged, they become a basis for standards, and standards become a basis for performance conversations. Operators should decide in advance how the data will be used, communicate that clearly, and avoid turning measurement into surveillance. The productivity gain depends on associates trusting the tool enough to use it honestly.</p><p>The Target upgrade is worth watching because it treats task sequencing, not software features, as the product. Stores recover hours when work is ordered well, and ordering requires a single rule set, a traffic-aware schedule and a baseline that makes the result checkable.</p><p>The practical sequence is instrumentation first, then a visible ranking rule, then a weekly exception review. Each step is cheap, and together they turn an app refresh into a measurable change in how store hours are spent. The return on that discipline compounds, because every later decision about layout, assortment or staffing can be compared against the same baseline instead of argued from opinion.</p><ul><li><a href="https://www.retaildive.com/news/target-upgrades-store-operations-app-employees/832989/" target="_blank">Target wants more efficient stores. An upgraded employee app could hel</a></li><li><a href="https://www.retaildive.com/news/monthly-retail-sales-from-the-us-commerce-department/574252/" target="_blank">High prices push September retail sales up 6.7% over last year</a></li><li><a href="https://www.retaildive.com/news/tractor-supply-opens-idaho-distribution-center-with-automation-dedicated-a/832591/" target="_blank">Tractor Supply opens Idaho distribution center with automation, dedica</a></li><li><a href="https://www.retaildive.com/news/nordstrom-expands-fao-schwarz-offerings-new-app-features-holiday/832853/" target="_blank">Nordstrom expands FAO Schwarz offerings, debuts new app features for h</a></li></ul><p><strong>Why does task sequencing matter more than app features?</strong></p><p>A: Because associates already have the tools to complete tasks; what they lack is a rule for deciding which task to do next. Sequencing inside one app replaces four competing priority systems with a single visible order.</p><p><strong>How many hours can a store realistically recover?</strong></p><p>A: It varies by format and traffic, but the recoverable share usually sits in travel, waiting and rework rather than in task execution itself. Operators should establish a baseline before quoting any figure.</p><p><strong>What data should the app capture?</strong></p><p>A: At minimum, task start and completion times, the location where the task happened, and whether it was completed as planned. Adding the reason for deferral makes the data far more useful for weekly reviews.</p><p><strong>How do you avoid turning the app into surveillance?</strong></p><p>A: Decide the purpose before rollout, limit data collection to task-level events rather than individual movement, and publish how the data will and will not be used. Trust is a precondition for honest logging.</p><p><strong>Does this approach work for small chains?</strong></p><p>A: Yes, at lower cost. A shared spreadsheet with task times and a weekly review captures much of the benefit. The app mainly automates the collection and the ranking, not the underlying discipline.</p><ul><li><a href="https://www.retaildive.com/news/target-upgrades-store-operations-app-employees/832989/" target="_blank">https://www.retaildive.com/news/target-upgrades-store-operations-app-employees/832989/</a></li><li><a href="https://www.retaildive.com/news/monthly-retail-sales-from-the-us-commerce-department/574252/" target="_blank">https://www.retaildive.com/news/monthly-retail-sales-from-the-us-commerce-department/574252/</a></li><li><a href="https://www.retaildive.com/news/tractor-supply-opens-idaho-distribution-center-with-automation-dedicated-a/832591/" target="_blank">https://www.retaildive.com/news/tractor-supply-opens-idaho-distribution-center-with-automation-dedicated-a/832591/</a></li></ul><!--SEO Title: Target Moves Task Logic to Handhelds to Reclaim HoursMeta Description: Target is rebuilding its employee app around task sequencing, a move that treats labor hours as the scarce resource in store operations.Canonical URL: https://www.bxtdata.com/insights/target-employee-app-task-logic-->
博晓通-用户增长分析师-赵雪
2026-10-17
Target Store App Upgrade Moves Data to the Frontline
<p>Target is upgrading the app store associates use for daily tasks, part of a broader push to put operational data and task routing directly in frontline hands. The operational logic is straightforward: faster task handoff and better availability signals. The sentiment logic is less obvious and more valuable. When frontline staff can see the same demand and inventory data that corporate systems see, the advice they give customers becomes consistent, and consistency is the single largest driver of service-related sentiment scores.</p><p>The first conclusion is that frontline tooling is a sentiment lever, not only an efficiency lever. <mark style="background:#024e9a12;">Target is upgrading the app store associates use for daily tasks</mark><a href="https://www.retaildive.com/news/target-upgrades-store-operations-app-employees/832989/" target="_blank">Retail Dive</a>, which changes what staff can answer when a customer asks whether an item is in stock or when it will arrive. Inconsistent answers are the most common source of negative reviews about service, and they originate in information asymmetry rather than attitude. Closing that gap moves sentiment without any change to staffing.</p><p>The second conclusion is that the value of the tool depends on the quality of the underlying demand signal. <mark style="background:#024e9a12;">the parent company behind Bed Bath and Beyond is using AI to unify forecasting and replenishment</mark><a href="https://www.supplychaindive.com/news/bed-bath-beyond-parent-company-taps-ai-to-unify-forecasting-replenishmen/832759/" target="_blank">Supply Chain Dive</a>, replacing fragmented spreadsheets with a single demand signal. If the app surfaces a forecast that conflicts with what the store actually sees, staff stop trusting it within weeks. Trust in the tool is built by making its predictions verifiable at store level.</p><h3>Why task routing changes service outcomes</h3><p>Task routing changes service outcomes because it determines whether an associate is available when a customer needs them. When tasks are pushed by a central queue without regard to store conditions, staff are pulled away at exactly the moments when traffic peaks. Letting the store adjust sequence while keeping the priority list fixed gives both consistency and flexibility. The measurable effect shows up as reduced wait times and fewer abandoned enquiries rather than as labour savings.</p><h3>How availability accuracy drives reviews</h3><p>Availability accuracy drives reviews directly because a wrong in-stock signal creates a failed trip. Customers who arrive expecting an item and find it missing describe the experience as misleading rather than merely inconvenient, and that framing produces harsher reviews. Improving the accuracy of the signal shown to staff, and therefore to customers, has a larger sentiment effect than shortening the delivery promise. Accuracy is a cheaper lever than speed.</p><h3>Make the forecast verifiable at store level</h3><p>Best practice is to make the forecast verifiable at store level, so associates can see whether the prediction matched reality and flag discrepancies in one action. A tool that cannot be corrected loses credibility, and an untrusted tool is ignored regardless of its technical quality. The design requirement is a single, low-friction correction path with visible follow-through, because staff stop reporting when previous reports produced no change.</p><h3>Track sentiment by store, not only by chain</h3><p>The second practice is to track sentiment by store rather than only by chain average. Chain averages hide the stores where tooling adoption is weak, and adoption is the variable that determines whether the investment produces results. Pairing adoption metrics with review sentiment by store identifies which locations need coaching, and turns a national rollout into a targeted improvement programme with a clear owner per location.</p><p>A common mistake is measuring frontline tooling purely on task completion speed. Speed improves even when the tool is degrading the customer interaction, because associates optimise for the metric they are shown. Pairing speed with a service metric, such as enquiry resolution rate or repeat visit within thirty days, prevents the tool from quietly transferring work from the back office to the shop floor.</p><p>A second mistake is rolling out the tool without adjusting store targets. When the app adds responsibilities, associates absorb them within existing hours, which reduces time available for customer interaction. Aligning targets and staffing to the new task set is what converts a tooling upgrade into a service improvement rather than an increase in workload at constant pay.</p><p>The supporting evidence from the same period points in the same direction. Retailers that invest in distribution and fulfilment accuracy are tightening replenishment cycles rather than simply adding capacity. <a href="https://www.supplychaindive.com/news/walmart-opens-next-gen-california-facility-to-boost-west-coast-fulfillmen/832631/" target="_blank">Supply Chain Dive</a> Tractor Supply opened a distribution centre with automation and a dedicated AI team, and the reported benefit is shorter replenishment cycles rather than lower headcount. Accuracy at the upstream layer is what makes downstream frontline tools trustworthy.</p><p>App-based member engagement is being used in the same way. Bealls launched its first mobile app marketing campaign and tied installs to store traffic and member data capture rather than standalone digital orders. <a href="https://www.retaildive.com/news/bealls-debuts-mobile-app-marketing-campaign/832855/" target="_blank">Retail Dive</a> The pattern is consistent: the app is treated as an instrument for capturing and returning intent, not as a separate sales channel. Frontline tooling follows the same logic, which is why sentiment and operations are converging in the same product roadmap.</p><p>In summary, upgrading the associate app is a sentiment intervention as much as an efficiency one. Consistent answers depend on shared data, and shared data depends on forecasts that store teams can verify and correct. The tool succeeds when staff trust it, and staff trust it when their corrections visibly change something.</p><p>Three actions follow. Make the forecast verifiable at store level with a single low-friction correction path. Track adoption and sentiment by store rather than by chain average. And align store targets and staffing to the new task set so the upgrade improves service instead of shifting workload. Together these turn a tooling investment into a measurable service outcome.</p><ul><li><a href="https://www.retaildive.com/news/target-upgrades-store-operations-app-employees/832989/" target="_blank">Retail Dive: Target upgrades store operations app for employees</a></li><li><a href="https://www.supplychaindive.com/news/bed-bath-beyond-parent-company-taps-ai-to-unify-forecasting-replenishmen/832759/" target="_blank">Supply Chain Dive: Bed Bath and Beyond parent taps AI to unify forecasting and replenishment</a></li><li><a href="https://www.supplychaindive.com/news/walmart-opens-next-gen-california-facility-to-boost-west-coast-fulfillmen/832631/" target="_blank">Supply Chain Dive: Walmart opens next gen California facility for west coast fulfillment</a></li><li><a href="https://www.retaildive.com/news/bealls-debuts-mobile-app-marketing-campaign/832855/" target="_blank">Retail Dive: Bealls debuts mobile app marketing campaign</a></li><li><a href="https://www.retaildive.com/news/tractor-supply-opens-idaho-distribution-center-with-automation-dedicated-a/832591/" target="_blank">Retail Dive: Tractor Supply opens Idaho distribution center with automation</a></li></ul><p><strong>Why is frontline tooling a sentiment lever?</strong></p><p>A: Because inconsistent answers are the most common source of negative service reviews, and they come from information asymmetry rather than attitude. Sharing the same demand and inventory data closes that gap without changing staffing.</p><p><strong>What makes an associate tool trusted?</strong></p><p>A: A forecast that can be verified at store level and corrected in one low-friction action with visible follow-through. Staff stop reporting when previous reports produce no change.</p><p><strong>Why track sentiment by store rather than by chain?</strong></p><p>A: Chain averages hide locations where adoption is weak. Pairing adoption metrics with review sentiment by store identifies which locations need coaching and assigns a clear owner.</p><p><strong>What is the risk of measuring only task completion speed?</strong></p><p>A: Speed improves even when the customer interaction degrades, because associates optimise for the metric they are shown. Pairing speed with a service metric prevents workload shifting to the shop floor.</p><p><strong>Why must store targets be adjusted at rollout?</strong></p><p>A: The app adds responsibilities that associates absorb within existing hours, reducing time for customer interaction. Aligning targets and staffing converts tooling into service improvement rather than added workload.</p><p><strong>How does upstream accuracy affect the frontline app?</strong></p><p>A: Staff trust the app only if its signals match what they observe. Tighter replenishment cycles and accurate availability upstream are what make downstream frontline tools credible.</p><ul><li><a href="https://www.retaildive.com/news/target-upgrades-store-operations-app-employees/832989/" target="_blank">Retail Dive: Target upgrades store operations app for employees</a></li><li><a href="https://www.supplychaindive.com/news/bed-bath-beyond-parent-company-taps-ai-to-unify-forecasting-replenishmen/832759/" target="_blank">Supply Chain Dive: Bed Bath and Beyond parent taps AI to unify forecasting and replenishment</a></li><li><a href="https://www.retaildive.com/news/bealls-debuts-mobile-app-marketing-campaign/832855/" target="_blank">Retail Dive: Bealls debuts mobile app marketing campaign</a></li></ul><!--SEO Title: Target Store App Upgrade Moves Data to the FrontlineMeta Description: Target upgrades its store operations app for associates. This analysis covers frontline data trust, availability accuracy, store-level sentiment tracking and target alignment.Canonical URL: https://www.bxtdata.com/insights/Target-Store-App-Upgrade-Moves-Data-to-the-Frontline-->
博晓通-零售分析师-高翔
2026-10-17
Surcharge Stacking Resets Last-Mile Cost Before December
<p>Parcel pricing is heading for a record high in the fourth quarter. According to the TD Cowen/AFS Freight Index, easing fuel costs and a rebound in discounting offered shippers some relief through the third quarter, but peak season surcharges will reverse that trend as holiday volume builds. For retail operations teams, the implication is direct: last-mile cost per order will rise faster than headline shipping rates, and the gap between carriers with negotiated capacity and those without will widen sharply before December.</p><p>The mechanics behind the increase are worth separating from the headline. Base rates and surcharges move on different clocks. Base rates are set through annual negotiations and change slowly, while peak surcharges are triggered by volume thresholds and can reset within weeks. A retailer that budgeted for a modest increase in base rates may still see a materially higher blended cost once residential delivery, oversize handling and additional handling fees stack on top of the peak component.</p><p>Fuel was the one line item that moved in the retailer's favour through the third quarter. Lower diesel prices reduced the fuel surcharge component that carriers apply as a percentage of base rates. That relief, however, is mechanical and reversible. Fuel surcharges are indexed, so a modest move in diesel prices feeds directly into per-package cost, and carriers rarely delay the pass-through when the index rises.</p><p>Capacity allocation matters more than headline price in a tightening market. Carriers ration peak capacity through contract terms rather than through open-market pricing. Retailers with committed volume and consistent tender acceptance rates keep access to primary capacity, while those that tender irregularly get pushed into the spot market where rates are set by scarcity. The practical result is that two retailers shipping identical parcels from the same origin can face very different costs in December.</p><p>Both major carriers have signalled that the fourth quarter will be the most expensive on record. That framing is useful because it shifts the planning question from whether costs will rise to how much of the increase can be offset by changes in how parcels are packed, routed and promised to customers.</p><p>The third-quarter relief came from two sources that are both temporary. Lower fuel prices reduced the indexed fuel surcharge, and a rebound in promotional activity increased parcel volume, which improved carriers' fixed-cost absorption and moderated the pressure to raise rates. Neither factor is structural, and both can reverse within a single quarter as fuel prices recover and promotional intensity normalises.</p><p>The important distinction for planning is between cost drivers a retailer controls and those it does not. Fuel, base rate increases and peak surcharge triggers sit outside the retailer's control. Packaging density, order splitting rules, delivery promise windows and carrier mix sit inside it. Planning cycles that treat all cost lines as fixed tend to overestimate exposure and underestimate the available offsets.</p><p>Tender acceptance rate has become the single most predictive metric of landed parcel cost. A retailer whose tenders are accepted at a high rate stays on primary capacity and pays contract rates; a retailer whose tenders are rejected repeatedly is routed to the spot market, where the same parcel can cost materially more. Improving tender acceptance is therefore a cost programme, not just a service programme.</p><p>Improving acceptance starts with smoothing volume across the week. Carriers price and allocate against daily capacity, and a retailer that concentrates shipments on Monday and Tuesday creates predictable rejection risk. Spreading volume and aligning pick-and-pack schedules with carrier cut-off windows raises acceptance without changing total volume, and the effect on cost is usually larger than any negotiated discount.</p><p>A second lever is dimensional compliance. Carriers increasingly apply dimensional weight pricing, so a parcel that is light but bulky is charged as if it were heavy. Auditing packaging against dimensional rules and redesigning cartons around actual product dimensions reduces billed weight directly, and the effect compounds with the peak surcharge because surcharges apply to the billed amount rather than the physical weight.</p><h3>Smooth volume across the shipping week</h3><p>Carriers allocate capacity against daily limits. Concentrating shipments into the first two days of the week raises rejection risk and pushes volume into spot pricing. Spreading shipments and aligning packing schedules with carrier cut-off windows improves tender acceptance without changing total volume.</p><h3>Audit packaging against dimensional weight rules</h3><p>Light but bulky parcels are billed as if heavy under dimensional weight pricing. Redesigning cartons around actual product dimensions lowers billed weight directly, and the saving compounds because peak surcharges are calculated on the billed amount. Packaging audits should therefore run before peak season rather than during it, when engineering capacity is already committed and carton changes cannot be introduced without disrupting pick lines.</p><h3>Model cost per order rather than shipping rate</h3><p>Peak surcharges, residential and additional handling fees stack on top of base rates. Track blended cost per order by channel and by service level, so that the true exposure is visible before surcharge announcements land. A single blended number across all channels will hide the services where exposure is concentrated, which are usually the ones the marketing calendar depends on most.</p><h3>Reserve primary capacity with committed volume</h3><p>Contract terms, not open-market pricing, determine peak capacity. Commit realistic volume and maintain consistent tender behaviour to stay on primary capacity, and treat tender acceptance rate as a weekly operational metric rather than an annual review item. Carriers reward predictability, so a retailer that tenders consistently at moderate volume usually retains better access than one that tenders erratically at higher volume.</p><p>Treating shipping cost as a single negotiated rate is the most common planning error. Base rates, fuel surcharges and peak surcharges move independently and on different schedules. A budget built on the base rate alone will systematically understate the fourth-quarter cost increase and will not identify where offsets are available.</p><p>A second mistake is optimising for the lowest quoted rate per parcel. A carrier with a low headline rate but unstable tender acceptance will push volume into the spot market, and the blended cost will exceed that of a carrier with a higher quoted rate and reliable capacity. Cost per delivered order, not quoted rate, is the metric that reflects reality.</p><p>Parcel cost in the fourth quarter will be shaped by three forces that move on different clocks: indexed fuel surcharges, annual base rate increases and volume-triggered peak surcharges. The first is reversible, the second is slow and the third is the one that determines whether the quarter sets a record. Retailers that manage packaging density, shipping rhythm and carrier mix can offset a meaningful share of the increase.</p><p>The practical takeaway for retail operations teams is to move parcel cost management from an annual negotiation event to a weekly operating discipline. Track blended cost per order, monitor tender acceptance, and audit packaging against dimensional rules on a continuous basis. Those three actions do not require carrier concessions and they compound as volume grows into the holiday peak.</p><ul><li><a href="https://www.supplychaindive.com/news/fedex-ups-delivery-prices-set-for-record-high-q4/832992/" target="_blank">FedEx, UPS delivery prices set for record-high Q4</a></li><li><a href="https://www.supplychaindive.com/news/5-trends-defining-consumer-electronics-supply-chains/832717/" target="_blank">5 trends defining consumer electronics supply chains</a></li><li><a href="https://www.supplychaindive.com/news/panama-canal-challenges-drive-shippers-to-port-of-los-angeles/832748/" target="_blank">Panama Canal challenges drive shippers to Port of Los Angeles</a></li></ul><p><strong>Why will parcel costs peak in the fourth quarter?</strong></p><p>A: Peak season surcharges are volume-triggered and reset within weeks, while base rates are set annually. As holiday volume builds, surcharges stack on top of base rates and push blended cost per order to a record high.</p><p><strong>Did lower fuel prices help retailers?</strong></p><p>A: Yes, but only temporarily. Lower diesel prices reduced the indexed fuel surcharge in the third quarter. The relief is mechanical and reversible, and it feeds directly back into per-package cost when the index rises.</p><p><strong>What is tender acceptance rate?</strong></p><p>A: It is the share of shipment tenders a carrier accepts rather than rejects. A high rate keeps a retailer on primary contract capacity; repeated rejections push volume into the spot market at materially higher rates.</p><p><strong>How does dimensional weight affect cost?</strong></p><p>A: Light but bulky parcels are billed as if they were heavy. Redesigning cartons around actual product dimensions lowers billed weight, and the saving compounds because peak surcharges apply to the billed amount.</p><p><strong>Why not simply choose the carrier with the lowest rate?</strong></p><p>A: A low quoted rate paired with unstable tender acceptance pushes volume into spot pricing, and the blended cost can exceed that of a carrier with a higher quoted rate and reliable capacity.</p><p><strong>What should retailers track weekly?</strong></p><p>A: Blended cost per order by channel and service level, tender acceptance rate, and packaging compliance against dimensional weight rules. All three are within the retailer's control and none require carrier concessions.</p><ul><li><a href="https://www.supplychaindive.com/news/fedex-ups-delivery-prices-set-for-record-high-q4/832992/" target="_blank">FedEx, UPS delivery prices set for record-high Q4</a></li><li><a href="https://www.supplychaindive.com/news/5-trends-defining-consumer-electronics-supply-chains/832717/" target="_blank">5 trends defining consumer electronics supply chains</a></li><li><a href="https://www.supplychaindive.com/news/panama-canal-challenges-drive-shippers-to-port-of-los-angeles/832748/" target="_blank">Panama Canal challenges drive shippers to Port of Los Angeles</a></li></ul><!--SEO Title: Surcharge Stacking Resets Last-Mile Cost Before DecemberMeta Description: Fourth-quarter parcel pricing is set to reach a record high as peak surcharges stack on top of base rates. This analysis separates the cost drivers retailers control from those they do not, and sets out packaging, shipping rhythm and carrier mix actions that offset the increase.Canonical URL: https://www.bxtdata.com/insights/Surcharge-Stacking-Resets-Last-Mile-Cost-Before-December-->