The youngest shoppers are being described by retail researchers as having their brains rewired by AI at the same moment they are craving physical experiences. The oldest members of Gen Alpha, a generation researchers date from around 2010, are now learning to drive, which means retailer attention is shifting from observing them to selling to them. The pattern that matters for brands is not that these shoppers use AI, but that they use it before they ever reach a product page, which relocates the moment a brand can be chosen.
What Makes This Generation Different
Retail Dive’s analysis describes the youngest Gen Zs and oldest Gen Alphas as price-sensitive, digitally savvy and drawn to physical retail experiences. They influence household purchases despite having little money of their own. That combination is unusual in retail history: previous generations with limited spending power had limited influence, while this one has influence without transaction volume.
The AI exposure is the new variable. A shopper who has always had a model available to summarize options does not browse in the same way. They arrive with a shortlist already formed, often without knowing which brands were excluded and why. For a brand, being absent from that shortlist is a silent loss, because there is no failed click to measure.
Influence Without a Wallet
Household purchase influence means the category implications run through parents. A child who asks for a specific brand by name converts a household decision into a specified purchase, which shifts power from the parent’s price comparison to the child’s preference. Brands that win this generation early are effectively pre-selling to the person who holds the budget.
Why Physical Retail Still Wins Attention
The same research notes a craving for physical experiences that coexists with heavy digital use. This is not nostalgia. Digital saturation raises the marginal value of anything that cannot be replicated on a screen, and a store visit is one of the few remaining experiences that a model cannot simulate. For categories where touch, fit or smell matters, the store becomes a discovery channel rather than a fulfillment channel.
There is a pricing consequence too. Circana’s survey of more than 3,500 shoppers put expected holiday budgets at 779 dollars, below 796 dollars in 2025, while Simon-Kucher projected a 5.5 percent decline. A generation that is price-sensitive and experience-seeking will spend where the experience justifies the premium and default to the cheapest option everywhere else, which compresses the middle of the assortment.
The Middle of the Range Gets Squeezed
The squeeze is already visible in adjacent categories. Aspirational luxury has been contracting as the consumer who bought slightly above their means pulls back. The same logic applies to mid-tier products aimed at young shoppers: if the purchase is not an experience and not the cheapest option, it has no reason to exist in the consideration set.
How Discovery Actually Happens Now
Discovery has split into two paths. The first is social video, where a product is encountered inside entertainment and the brand is a supporting character. The second is conversational search, where a model answers a question and names a few options. The two paths reward different things: social video rewards visual distinctiveness, conversational search rewards verifiable facts and clear category language.
Most brands invest in the first and neglect the second, because the first has visible metrics. The second has no dashboard, so it gets treated as a technical concern rather than a marketing one. That gap is where competitive advantage currently sits, because a brand that is described accurately by models gets recommended in conversations it never sees.
What to Fix First
Start with the product page. If a model were asked what this product is for, who it suits and what it costs, the page should answer all three in plain language within the first screen. Most pages fail the third question because pricing is hidden behind a variant selector, and hidden pricing is the most common reason a model omits a brand from a recommendation.
Then fix the comparison layer. Shoppers in this generation compare across brands constantly, and a brand that publishes an honest comparison of its own weaknesses is more likely to be cited than one that only lists strengths. Verifiable specificity is the currency, not enthusiasm.
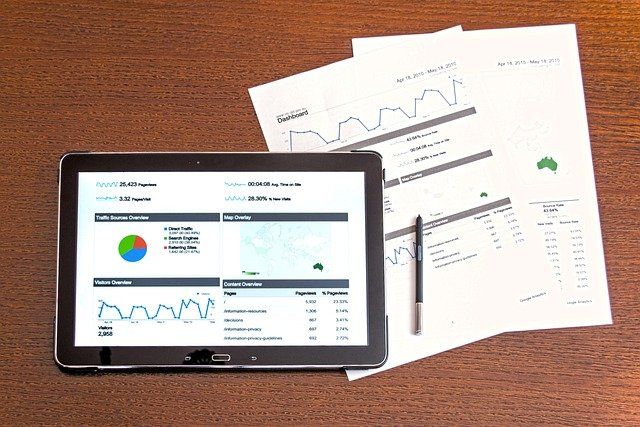
Finally, measure the invisible. Set up a monthly check of how models describe the brand, which attributes are mentioned and which are missing. The exercise is cheap and it surfaces content gaps faster than any analytics dashboard, because it shows what a shopper is told before they arrive.
The Measurement Gap Nobody Owns
Conversational discovery has no owner in most retail organizations. Social teams own video, performance teams own paid search, and nobody owns the answer a model gives when a shopper asks for a recommendation. The result is that the channel with the fastest-growing influence has the weakest measurement, and budgets follow measurement rather than influence.
Closing the gap does not require a new platform. A monthly log of prompts, recorded answers and a short assessment of accuracy is enough to establish a baseline. Once the baseline exists, changes in brand description become visible, and visible problems get funded. Invisible ones do not.
A Monthly Prompt Audit
Twenty prompts are enough to start: category questions, comparison questions, price questions and suitability questions. Record what the model says, flag anything wrong, and route the correction to whoever owns the relevant page. The audit takes an afternoon and produces a list of content fixes that no analytics tool would surface.